Become a job-ready residential loan processor — without learning it the hard way
Most processors learn by surviving. This curriculum gives you the file-review instincts, compliance grounding, and professional habits before your first real pipeline.
"The goal isn't just to understand mortgage lending — it's to work inside it, confidently, from your very first file."
— Shirley Allen
What you'll learn
What you'll be able to do
- Accurately review and condition a complete mortgage loan file from 1003 application through final approval, catching deficiencies before underwriting.
- Read and interpret credit reports, debt-to-income ratios, and automated underwriting system (AUS) findings for Fannie Mae, Freddie Mac, FHA, and VA loan types.
- Order, track, and clear the four critical third-party verifications — appraisal, title, flood cert, and HOI — on schedule without pipeline stalls.
- Apply RESPA, TRID, and HMDA compliance rules to real processing scenarios, correctly completing Loan Estimates and Closing Disclosures within regulatory deadlines.
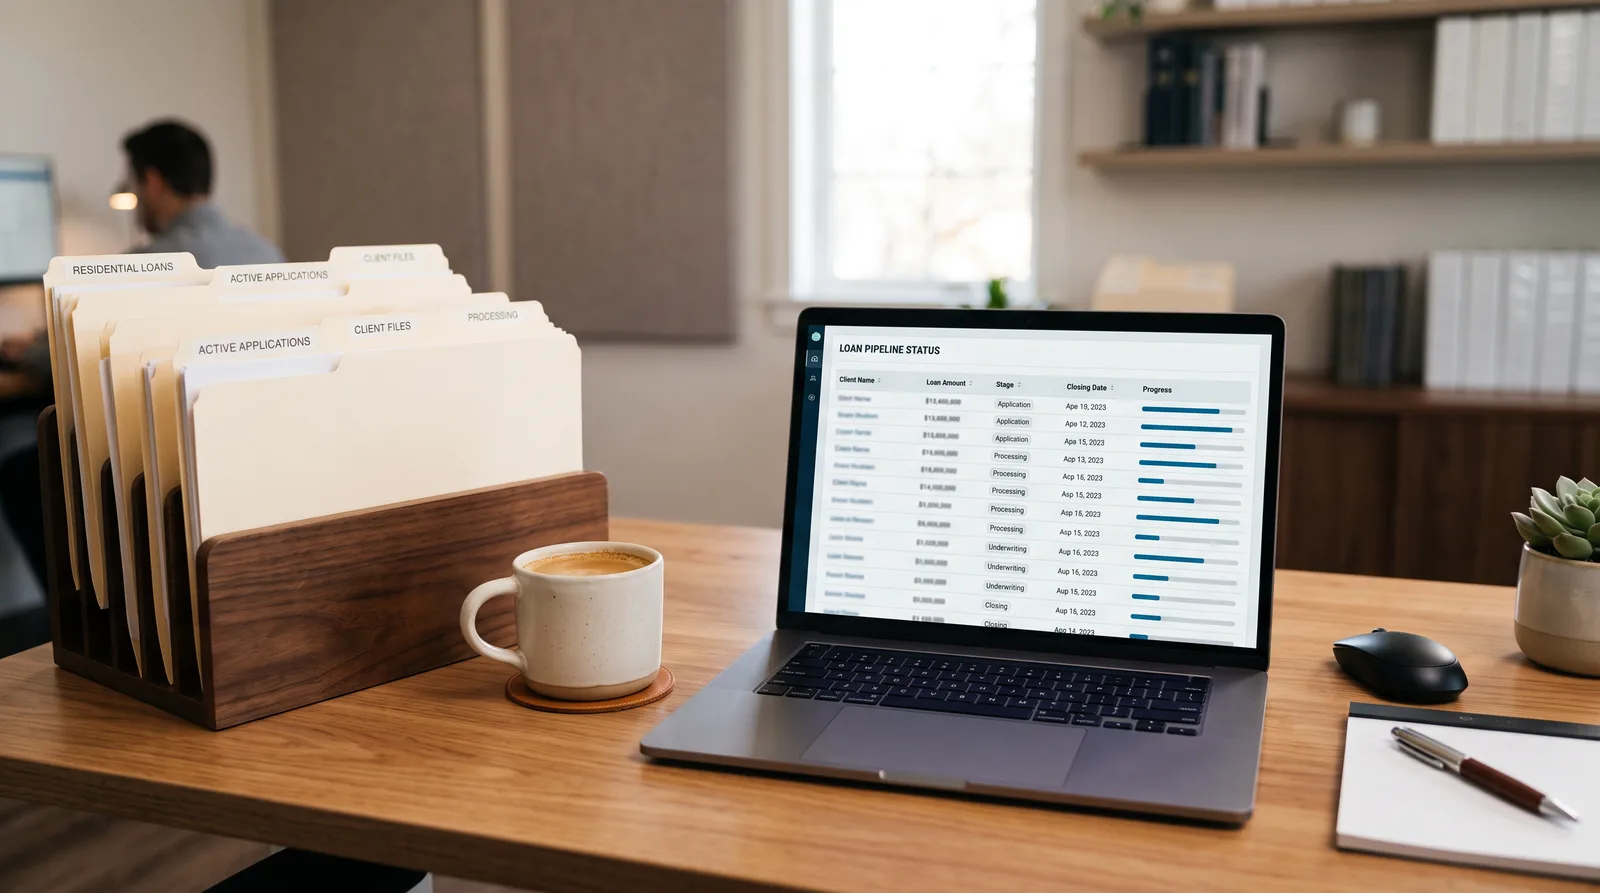
- Build and manage a live loan pipeline using industry-standard Loan Origination Software (LOS) workflows, status notes, and condition tracking.
- Communicate condition requests, approval decisions, and closing timelines confidently and professionally to borrowers, realtors, and loan officers.
How it works
A school that adapts to you
This isn't a set of static videos. Every lesson is generated live and tuned to where you actually are.
We learn your level
A quick placement check tailors your starting point so you're never bored or lost.
Lessons adapt as you go
Each lesson is written for your pace and your goal, adjusting as your skills grow.
Your AI coach keeps you moving
Checkpoints, feedback, and gentle nudges turn progress into a real result.
The curriculum
What's inside your school
8 modules · 38 lessons
The Mortgage Industry & Processor's Role
Orients students to residential lending, key players, loan types, and the processor's daily responsibilities at the desk.
- 1.1How Residential Lending WorksIncluded
- 1.2The Processor's Role on the Lending TeamIncluded
- 1.3Loan Types at a Glance: Conventional, FHA, VA, and USDAIncluded
- 1.4The Loan Lifecycle from Application to FundingIncluded
Application Intake & the 1003
Teaches students to accurately capture, review, and validate the Uniform Residential Loan Application — the foundation of every file.
- 2.1Anatomy of the Uniform Residential Loan Application (1003)Included
- 2.2Spotting Incomplete and Inconsistent Application DataIncluded
- 2.3Borrower Identity, Occupancy, and Property Purpose VerificationIncluded
- 2.4Building the Initial Loan File and ChecklistIncluded
Credit, Income, and AUS Analysis
Develops the analytical skills to interpret credit reports, calculate qualifying ratios, and read AUS findings for all major loan programs.
- 3.1Reading and Interpreting a Tri-Merge Credit ReportIncluded
- 3.2Calculating Debt-to-Income RatiosIncluded
- 3.3Income Documentation: W-2, Self-Employed, and Non-Traditional SourcesIncluded
- 3.4Asset Verification and ReservesIncluded
- 3.5Running and Interpreting AUS Findings: DU and LPAIncluded
Third-Party Verifications & Due Diligence
Covers ordering, tracking, and clearing the four critical third-party services that every residential file requires.
- 4.1Appraisal Management: Ordering, Reviewing, and ConditioningIncluded
- 4.2Title Commitment Review and Title InsuranceIncluded
- 4.3Flood Zone Determination and Flood Insurance RequirementsIncluded
- 4.4Homeowners Insurance: Requirements, Review, and Common DeficienciesIncluded
- 4.5Building and Managing Your Third-Party Tracking LogIncluded
Compliance: RESPA, TRID, and HMDA
Applies federal mortgage compliance rules to real processing scenarios, with emphasis on accurate, on-time disclosure completion.
- 5.1RESPA Fundamentals and Prohibited PracticesIncluded
- 5.2TRID and the Loan Estimate: Rules, Tolerances, and DeadlinesIncluded
- 5.3The Closing Disclosure: Completing, Delivering, and CuringIncluded
- 5.4HMDA Data Collection and Reportable FieldsIncluded
- 5.5Compliance Scenarios: Catching Violations Before They CloseIncluded
LOS Workflows, Pipeline Management & Professional Communication
Builds job-ready skills in LOS navigation, active pipeline management, condition tracking, and confident stakeholder communication.
- 6.1Navigating an LOS: Screens, Fields, and File MilestonesIncluded
- 6.2Condition Tracking: Logging, Updating, and Clearing in the LOSIncluded
- 6.3Managing an Active Pipeline: Prioritization and Status NotesIncluded
- 6.4Communicating Conditions and Decisions to Borrowers and RealtorsIncluded
- 6.5From Clear-to-Close to Funding: Final File Review and HandoffIncluded
Mortgage Servicing Fundamentals
Covers what happens after a loan closes and is transferred or retained for servicing — payment processing, escrow administration, investor reporting, delinquency management, and the basics of loss mitigation and foreclosure.
- 7.1The Loan Servicing LifecycleIncluded
- 7.2Payment Processing and Escrow AdministrationIncluded
- 7.3Investor Reporting and Agency RemittanceIncluded
- 7.4Handling Delinquency: Early-Stage Default ManagementIncluded
- 7.5Loan Modifications, Workouts, and Foreclosure BasicsIncluded
Post-Closing: File Delivery, Investor Purchase, and Loan Sale
Covers everything that happens to the loan file after the transaction closes — final file assembly, shipping to the investor or warehouse lender, curing deficiencies, recording, and the loan sale and servicing transfer process.
- 8.1Post-Closing File Assembly and Stacking OrderIncluded
- 8.2Shipping the Loan to the Investor or Warehouse LenderIncluded
- 8.3Document Deficiencies and Suspense ConditionsIncluded
- 8.4Recording, Title Policy, and Final Title CommitmentIncluded
- 8.5Loan Sale, MERS Registration, and Transfer of ServicingIncluded
Who it's for
Is this you?
Career changers breaking in
You're coming from another field and need a structured, start-to-finish foundation before your first day at a lending desk.
New loan officer assistants
You support an LO and handle file prep, but you want to understand the full processing workflow so you can take on more and grow faster.
Junior processors leveling up
You've processed a few loans but learned on the fly — this curriculum formalizes your knowledge and fills the compliance gaps before a QC audit finds them.
Real estate agents going deeper
You want to understand what happens on the lending side after contract so you can set better borrower expectations and close more smoothly.
Processors moving to senior roles
You're ready to lead a pipeline or mentor junior staff, and you want the rigorous, documented framework that makes you the expert in the room.
Mortgage ops & compliance staff
You work in operations, underwriting support, or compliance and need a practical, end-to-end view of the processing workflow to do your job better.
Questions
Frequently asked
Shirley Allen
Welcome Students
Shirley Allen
If you've ever sat down at a processing desk — or hoped to — and felt like everyone around you already knew an unwritten rulebook that nobody handed you, I built this school for you.
The truth about mortgage processing is that it's a highly skilled profession that the industry has never been great at formally teaching. Most processors learn by doing: absorbing what they can from a senior colleague, surviving their first round of underwriter conditions, and slowly building a mental checklist of everything that can go wrong. That works — eventually. But it costs you time, it costs your pipeline deals, and it costs you confidence during the years when you most need it.
What I've tried to do with Affinity Mortgage Processing School is give you the structured foundation that the industry rarely puts in writing. We start with how residential lending actually works and where the processor fits on the team — not as a form-shuffler, but as the person who controls whether a loan moves or stalls. From there, we go deep: reading a tri-merge credit report the way an underwriter will, calculating DTI across every income type from W-2 to self-employed to non-traditional, running AUS findings in DU and LPA, and knowing what to do when the findings come back with conditions you've never seen before.
We spend serious time on the four third-party verifications that sink more pipelines than almost anything else — appraisal, title, flood, and HOI — and I show you how to build a tracking log that keeps every one of them moving without you having to carry it all in your head. And because compliance is non-negotiable in this industry, we walk through RESPA, TRID, and HMDA in plain English, with real scenarios where you practice catching violations before they become closing-day fires.
The last section brings it all together inside an LOS — how to navigate the system, log and clear conditions, manage a live pipeline by priority, and communicate professionally with borrowers, realtors, and loan officers when conditions come in, approvals land, or timelines shift.
Whether you're stepping into your first processor role, supporting a loan officer and ready to grow, or tightening up the skills you've been building on the job — this curriculum will give you the file-review instincts, the compliance grounding, and the professional habits to perform at a level that gets noticed. Come in ready to work. I'll show you exactly how it's done.
— Shirley Allen
Start your journey today
Get instant access — learn at your own pace with an AI coach in your corner.
$125/yr
Recurring billing · cancel anytime
Secure checkout · Instant access
- 8 modules, 38 lessons
- AI-adaptive lessons tuned to your level
- Quizzes & checkpoints to lock in progress
- Your own AI learning coach
- Learn on any device, at your pace
- Full access for as long as you're subscribed